Why customers want more than a scripted chatbot
A basic support bot responds to a narrow set of intents, often forcing customers through menus that do not reflect their situation. A personal-finance assistant can provide a more useful view by combining authorized account activity, customer preferences, and banking tools. It might categorize recurring subscriptions, summarize spending changes, project a near-term balance range, and remind a customer about a bill they asked to track.
“Autonomous financial advisor” needs careful definition. Organizing information and offering educational observations is different from providing individualized securities advice, recommending a financial product, or initiating a transaction. The bank should define the service’s scope with legal and compliance teams, assess applicable licensing and consumer-protection requirements, and avoid marketing a budgeting feature as a regulated advisor if it is not one.
A permissioned assistant architecture
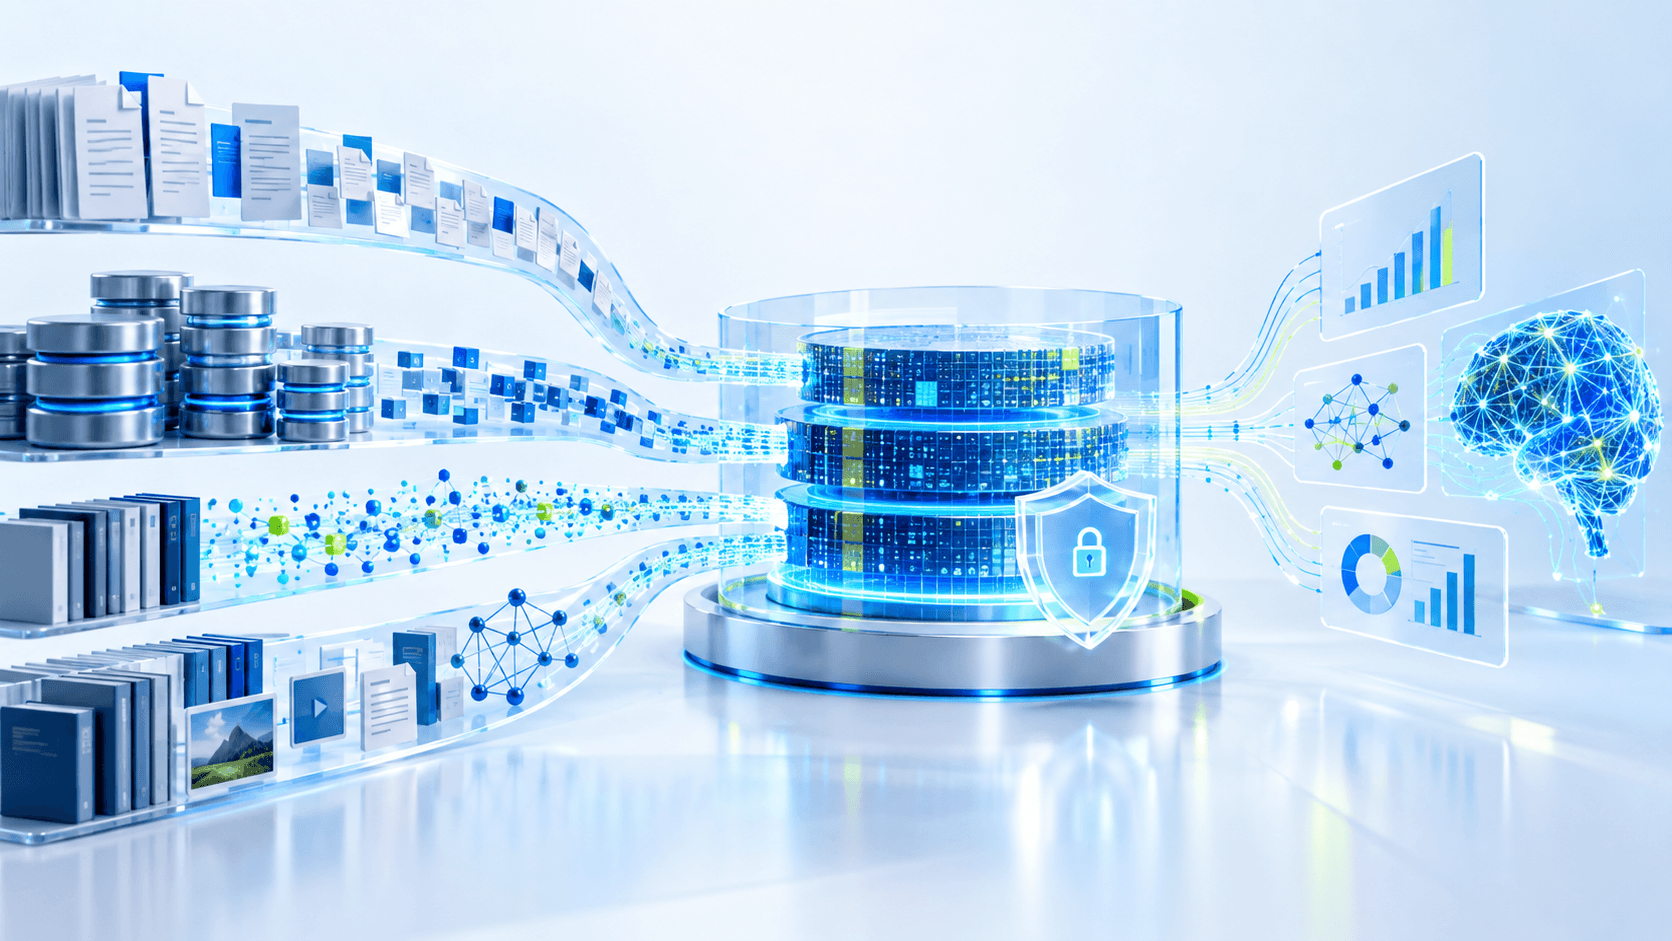
The assistant should retrieve only the customer’s authorized data, through existing identity and consent controls. A deterministic finance service—not a language model—should calculate balances, cash-flow projections, fees, or payment dates from validated transactions and explicit assumptions. The model can explain those results in plain language, while showing the time window, incomplete-data caveats, and sources behind an observation.
Subscription categorization can combine merchant normalization, rules, and a model that proposes a label. Let customers correct categories and mark transfers or shared expenses so the system learns within approved boundaries. A cash-flow projection should display assumptions and uncertainty, account for pending items when available, and avoid presenting a forecast as a guaranteed balance.
Keep financial actions under customer control
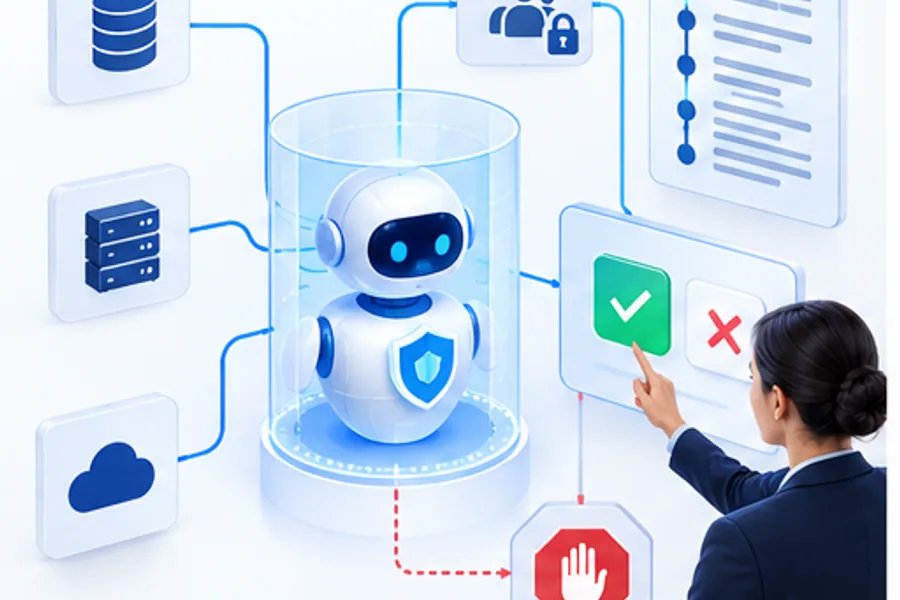
An assistant may surface a potential duplicate subscription, suggest a savings habit, or explain an available account feature. Before acting—such as cancelling a service, moving funds, opening an account, or placing an investment order—it should disclose the action and relevant terms, confirm the destination and amount, and obtain an explicit authorization through a secure transaction flow. Keep authentication, limits, and transaction execution in established banking systems.
Personalized savings recommendations should account for the customer’s stated goals, cash needs, fees, eligibility, and product disclosures. Investment or micro-investment recommendations can raise additional suitability, fiduciary, registration, and disclosure requirements depending on the service and jurisdiction. Do not have a general-purpose model invent a portfolio or promise returns. Route requests outside the approved scope to a qualified human or regulated service.
Design for trust, recourse, and privacy
Explain why an insight appeared and let a customer inspect and correct the underlying transactions. Provide an easy way to dismiss suggestions, disable proactive messages, manage data permissions, and reach a human. Avoid using sensitive inferences or manipulative urgency to nudge customers into products. Test recommendations and service outcomes across customer groups, including cases with limited history or irregular income.
Minimize data shared with models, keep account identifiers and credentials out of prompts, and control provider retention and support access. Log the version of the model, retrieved data, calculation result, customer consent, recommendation, and any approved action—without indiscriminately retaining full sensitive conversation content. Establish incident response, monitoring, vendor oversight, and a kill switch for both the assistant and each connected tool.
Show the assumptions behind a proactive cash-flow insight
A low-balance insight should identify the accounts and date range used, the known upcoming payments, and the assumptions about income or recurring transactions. A budgeting calculation service can produce a range or scenarios, while the model explains them. If salary timing is uncertain or an account connection is stale, show that limitation rather than present a single confident balance forecast.
Let the customer correct a recurring payment, exclude an internal transfer, or dismiss a mistaken pattern. Keep these corrections scoped to the authorized user and approved purpose. Evaluate whether customers understand the insight and can trace it to their own records. A technically accurate calculation may still be misleading if its explanation hides an important assumption.
Bind customer consent to the exact action and current state
If the customer chooses to move money after an insight, open the bank’s authorized transaction flow with the source account, destination, amount, timing, and relevant fees. Revalidate balances and constraints before execution. If any material detail changes after confirmation, obtain fresh authorization through that flow. A general opt-in to receive financial insights is not blanket permission for future transfers.
Test a disconnected account, a newly pending debit, an interrupted authorization, a duplicate action request, and a customer cancelling midway. Verify both the final account state and the explanation shown in the app. Provide a route to dispute or correct an action and disable proactive features. Keep product recommendations within the bank’s approved regulatory scope and avoid presenting a general budgeting assistant as a licensed investment adviser.
Launch with bounded autonomy and measurable value
Begin with read-only features such as subscription detection and a clearly qualified cash-flow summary. Evaluate transaction categorization accuracy, forecast error, correction rates, customer comprehension, opt-outs, complaints, and support handoffs. Shadow-test proactive insights before sending them, and let customers opt in to each type of notification.
Expand from suggestions to actions only when the bank has a documented legal basis, tested customer authorization, operational safeguards, and evidence that the feature improves customer outcomes. A next-generation mobile assistant should feel proactive without becoming opaque: it earns trust by showing its work, respecting permission, and asking before it acts.